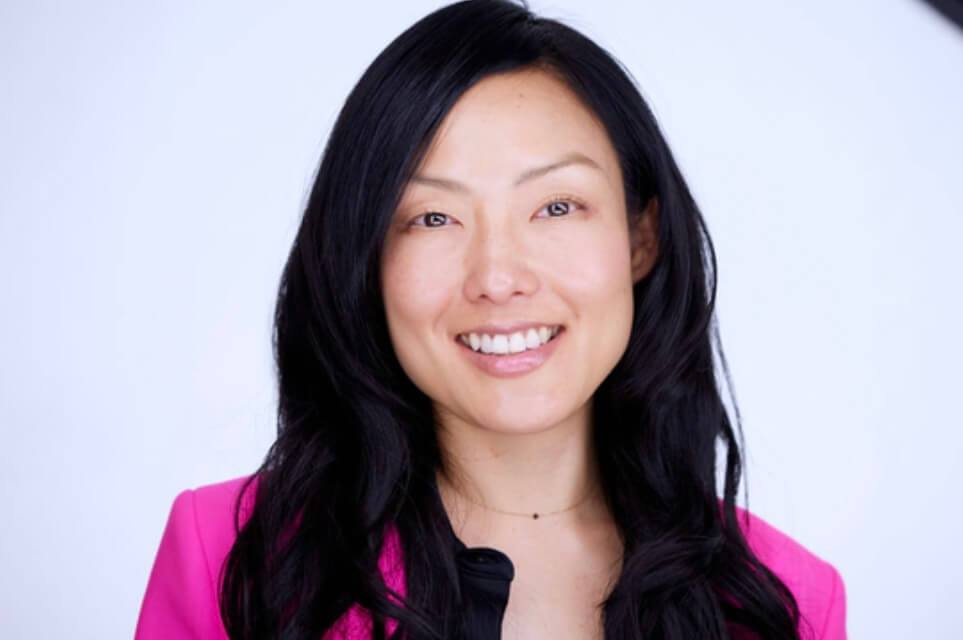
Jane Kim declared victory on Friday, November 6, in California's race for insurance commissioner after her opponent, state Senator Ben Allen, conceded — a result that puts the former San Francisco supervisor in charge of regulating the largest insurance market in the United States at the moment it is under its greatest strain in decades. The Associated Press has not yet issued a projection for the race, and California's count continues, but Allen's concession makes Kim the commissioner-elect who will succeed Ricardo Lara in January.
Source: CBS Los Angeles via Associated Press reporting
The latest semi-official figures published by the California Secretary of State on Friday evening, November 6, with all 23,860 precincts at least partially reporting, put Kim on 4,393,379 votes, or 53.0 percent, against 3,899,432 votes, or 47.0 percent, for Allen — a lead of just under 494,000 votes. Results remain semi-official while counties keep counting mail ballots that were postmarked by Election Day, and the statewide result is scheduled to be certified on December 11.
Source: California Secretary of State results via California Today
Allen telephoned Kim on Friday to concede. According to Insurance Journal's account of the call, Allen told her that “it appears that she has won” and that he wants her to succeed in the job. Kim, for her part, told supporters that Allen had called to congratulate her. The race was unusual in California politics: because of the state's top-two primary system, both finalists were Democrats, making this the first general election for insurance commissioner contested by two members of the same party.
Kim, 49, is a Stanford-educated attorney who served on the San Francisco Board of Supervisors and later ran Bernie Sanders's 2020 presidential campaign operation, according to campaign profiles. Supporters and industry publications have noted the historic character of the win: she is reported to be the first Korean American woman, and the first woman of color, elected California insurance commissioner. She entered the race late — she has said that as recently as September she would have been surprised to be running for the office at all.
The office she is taking over
The insurance commissioner leads the California Department of Insurance, the agency that licenses and regulates insurance companies, reviews and approves the rates they charge, enforces state insurance law and handles consumer complaints. It is one of the most powerful consumer-protection jobs in the state because almost every Californian must buy insurance — for a home, a car or a business — and the commissioner can decide how fast premiums rise and how companies must treat policyholders after a disaster.
The outgoing commissioner, Ricardo Lara, a Democrat first elected in 2018, has reached his term limit after two terms dominated by the collapse of the state's home-insurance market: major insurers stopped writing new policies in wildfire-prone areas, hundreds of thousands of homeowners were pushed onto the state FAIR Plan — the insurer of last resort — and the FAIR Plan itself won approval for a 29.1 percent homeowners rate increase that took effect on October 15, 2026, according to industry reporting. California home-insurance premiums rose about 22 percent above inflation between 2018 and 2022, the second-fastest increase in the country after Colorado, according to figures cited by CalMatters.
Kim's plan: “Natural Disaster Insurance for All”
Kim's signature proposal is a significant restructuring of how California covers disaster losses. She calls it “Natural Disaster Insurance for All”: a public, nonprofit state insurance program that would cover events such as wildfires, floods and earthquakes, funded through premiums, with part of the money directed to reducing future losses through wildfire prevention and home hardening. Under the plan, private insurers would continue to administer policies and handle routine claims, while the public program would carry the disaster risk. It would sit separately from the FAIR Plan, and Kim argues it would sharply reduce the number of Californians forced to rely on the FAIR Plan at all.
Kim has acknowledged the program would require approval from the state Legislature and would take years to build. Her wider platform includes limiting what she calls excessive insurer profits, penalising companies that delay claims, cracking down on illegal price-gouging, and publishing insurers' performance and claims-handling records so consumers can compare them. Both she and Allen pledged to refuse campaign contributions from the insurance industry, saying the regulator must be independent of the companies it regulates.
Allen's case, and why he lost the argument
Allen, a state senator whose district includes Los Angeles County communities hit by the January 2025 fires, argued for reforming the existing market rather than replacing its disaster layer. He warned that Kim's public disaster program could cost California billions of dollars. His own platform promised faster reviews of insurance rates and policies, incentives for home hardening, larger upfront payments to policyholders for personal-property losses, and low-interest loans to help homeowners reduce wildfire risk — measures drawn from bills he authored in the Senate. He said helping constituents fight their insurers after the 2025 fires shaped his approach. In the June primary's crowded 11-candidate field, Kim finished first with 27.3 percent and Allen second with 19.4 percent; in the general-election campaign Allen actually raised more money — about $977,000 to Kim's more than $700,000, according to Insurance Journal — but it was not enough to close the gap.
California's insurance crisis is the leading edge of a national one: as wildfire, flood and storm risks climb, private insurers are retreating from whole regions and state-backed plans are swelling. Whether a public disaster-insurance program can work in the biggest state market will be watched by regulators across the United States — including in states where Punjabi-American families own homes, farms, trucking businesses and motels whose insurance bills have climbed steeply.
What it means for Punjabi and diaspora families
For California's large Punjabi community — concentrated in the Central Valley farming belt around Fresno, Yuba City, Stockton, Modesto and Bakersfield, and in trucking, gas-station and small-business ownership statewide — insurance is not an abstract issue. Farm properties, truck fleets, warehouses and family homes in and near wildfire and flood zones have faced the same non-renewals and FAIR Plan surcharges as everyone else, often with fewer alternatives. A commissioner who promises tougher claims enforcement and publishes insurer scorecards is directly relevant to any family that has had a claim delayed or a policy dropped; her public disaster program, if the Legislature enacts it, would be aimed at exactly the high-risk properties that private insurers have been abandoning.
What happens next
Counties will keep counting ballots for days, and the Secretary of State is scheduled to certify the statewide results on December 11. Kim is due to take office in January, when California's statewide officers are sworn in, and the first tests of her program will be legislative: her disaster-insurance plan needs a bill, hearings and a funding structure before it can cover a single home. Insurers, meanwhile, will be filing the rate requests that land on her desk from her first week — and her decisions on those filings, not her campaign promises, will set Californians' premiums in 2027.